Buying a condo
Ask early for the building’s insurance details and association rules. Bring your closing date and the lender’s written insurance needs. Then discuss what proof is needed and when.
Gather your documents ↗ Valley WestINSURANCE
CONDO INSURANCE · LAS VEGAS, NEVADA
Your building has a policy. Your unit has different needs. Let’s understand how the two fit together.
Request a condo quote Talk it through · (702) 262-9900Valley West Insurance is an agency, not the insurer. A request does not activate coverage.
THE SHORT ANSWER
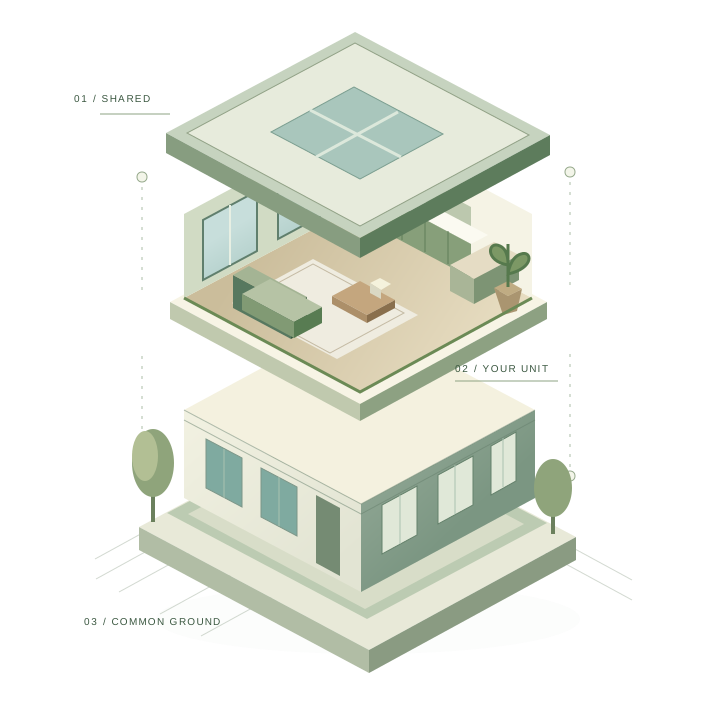
An HO-6 policy is insurance for a condo owner. It can help protect the parts of the unit you must insure, your things and your liability to others. It may also help with added living costs after a covered loss. The policy’s terms control.
It works alongside the association’s master policy. Don’t assume “inside is yours, outside is theirs.” The building, association rules, state law and both policies matter.
01 / A GOOD TIME TO LOOK CLOSER
Start with what has changed in your life or in your building.
Ask early for the building’s insurance details and association rules. Bring your closing date and the lender’s written insurance needs. Then discuss what proof is needed and when.
Gather your documents ↗Compare both renewal packets. Did the building’s insurer, or insurance company, change? Check deductibles (the share paid out of pocket) and which property is insured. Review your own limits too.
Check the shared exposure ↗A new kitchen, floor or built-in can change your needs. Keep a list of costs. Discuss the work before it starts, including the contractor’s insurance and any change in how you use the unit.
Look at unit improvements ↗02 / READ THE TWO POLICIES TOGETHER
“Bare walls,” “single entity” and “all-in” are shorthand. Read the full policy, its endorsements (changes to the policy) and the association declaration (the document that sets out key property rights and duties).
Start with the building and shared areas. Then check which parts of the units are insured. Look at original fixtures and the causes of damage the policy covers.
Compare the unit as first built with later upgrades. Ask who must insure each item. Check what each policy says it will cover.
A document review—not a universal “walls-in” rule.Review your things, your liability and added living costs after a covered loss. Check loss-assessment coverage and the parts of the unit you must insure too.
03 / MORE THAN THE WALLS
Start with these four areas. Check the policy’s limits and exclusions (what it does not cover). Read all changes to the policy too.
Review my condo coverage ↗Check which parts of the unit you must insure. Keep a record of new cabinets, floors and built-ins. The price you paid for the condo is not the cost to replace those items.
Your furniture, clothes and devices add up. Make a list. Ask if the policy pays to replace an item or takes off value for age and wear. Check special limits on jewelry and other valuables.
If you are legally at fault for harm to someone else or their property, liability coverage may help. The claim must meet the policy’s terms. A shared wall alone does not decide fault or who pays.
If a covered loss makes your unit unfit to live in, the policy may help pay the needed increase in living costs. Check which events qualify, how much it can pay and for how long. Ask which receipts to keep.
04 / THE EXPOSURE BETWEEN THE POLICIES
After a shared loss, the association may bill owners for part of the cost. Loss-assessment coverage may help if the loss and bill meet the policy’s terms. It does not pay every bill.
Bring the list of master-policy deductibles and the actual bill, if you have it. A coverage label alone does not answer these questions.
Routine upkeep, reserve funds and planned upgrades are generally outside this coverage. A cause the policy excludes or a cap on a type of loss can also leave costs with you.
Compare the deductible provision itself. A higher overall limit may not raise every smaller cap within the policy.
05 / REAL QUESTIONS, NO ASSUMED OUTCOME
Use these examples to plan your questions. They do not predict a claim result or decide who is at fault.
Note where the water came from, what it damaged and when you found it. Tell the association and your insurer promptly. Take photos and follow their instructions.
Ask: “Which policy covers the damaged building items, belongings and any temporary living expense?”
Building repairs, your things and fault may be separate questions. Keep the association’s notices and claim letters together.
Ask: “What facts and policy provisions determine responsibility, and are multiple insurers involved?”
A burst pipe, a slow leak, a sewer backup and a flood can have different rules. Standard policies commonly exclude flood, earthquake and wear. Other limits or added coverage may apply. Ask about the cause you have in mind.
06 / PREPARE FOR A USEFUL CONVERSATION
You don’t need every document to start a conversation. Having these nearby makes it easier to identify what still needs an answer.
This checklist runs only on this page. It does not save, upload or send documents, recommend limits, or produce a quote.
0 of 5 items gathered
07 / YOUR NEXT STEP
Tell us where the unit is, how you use it and when you need coverage. The insurer must review whether the risk fits its rules and which terms it can offer.
Buying, renewing or renovating? Share the timing and occupancy so the conversation starts in the right place.
Check who insures what, your share of a loss, the limits and what is not covered. Then compare the price.
A request or estimate is not coverage. Ask the agent or insurer to confirm the company, effective date (when coverage starts) and final terms before relying on protection.
THE QUESTIONS WORTH ASKING
It may cover parts of the unit. For some buildings with shared walls or stacked units, Nevada law goes beyond the outside of the building. Read the association’s policy and rules with your own policy. Review your upgrades, things and liability too.
Your lender or association may require coverage, certain limits or proof of insurance. Ask for the rules in writing. The association’s duties under state law are separate from what you must carry.
It may, based on the cause, the bill and the policy’s terms. Do not assume the full loss-assessment limit applies. Ask to see the terms and any added limits for the association’s deductible.
List the parts of the unit you must insure, the cost of your upgrades and your things. Bring the building’s insurance details. Review liability, loss of use and assessment limits separately. The condo’s sale value does not replace this review.
The unit, its location, how you use it and past claims can affect the quote. So can the limits, deductibles and options you choose. Compare the same coverage details across written offers. A lower price may mean you pay more of a loss, have less coverage or receive less for an older item.
Tell the agent before seeking or changing coverage. Long-term tenants, short-term rentals, part-time use and empty units can need different coverage and insurer review. An owner-occupied policy should not be assumed to fit a rental.
You can start a conversation and ask the association for current insurance information. Under NRS 116.31133(3), the insurer must issue a certificate or memorandum of insurance to a unit owner on written request. That summary does not replace the full policy when you need to check coverage.
KEEP EXPLORING
Sources checked November 12, 2026. This page explains general concepts. It is not a review of your policy or a claim decision. Insurer examples do not show which companies or policies Valley West can offer.
YOUR UNIT. YOUR QUESTIONS. A LOCAL CONVERSATION.
Start a condo coverage review with Valley West Insurance.
Request my condo review Or call (702) 262-9900Coverage and availability depend on insurer review and policy terms.
A request does not bind insurance.