Often not. A standard home insurance policy can treat an e-bike as a motor vehicle, and that can leave out both theft and crashes on the street. In the worked example below, a $3,200 e-bike stolen from a Henderson garage pays $0 under that wording. Checked September 27, 2026.
Nevada law does not require e-bike insurance. So the only cover you have is the cover you set up. Many Henderson riders find the gap after a theft or a crash, not before.
The fix is short. Ask your home insurer (the company that issues your policy) how its own policy treats an e-bike. Then fill any gap with an e-bike add-on, a separate e-bike policy, or both.
Key takeaways
- Nevada does not require it. State law keeps e-bikes out of the "motor vehicle" rules, so there is no registration and no required insurance.
- Your home policy may disagree. The standard home form calls any "self-propelled land" vehicle a motor vehicle, and it leaves most of those out.
- Theft and crashes are the two gaps. Under the standard wording, the bike itself and your street riding can both fall outside the policy.
- The risk is real. The CPSC counts an estimated 59,200 emergency room visits tied to e-bikes in 2024 alone.
- A fast bike is not an e-bike. No working pedals, or a motor over 750 watts, changes the legal category and the insurance answer.
In short
Home insurance usually covers a regular bicycle as part of your belongings. An e-bike often is not, because its motor can make it a "motor vehicle" in the policy's own words.
Read your policy for the motor vehicle wording, or ask your insurer in writing. If the answer is no, add e-bike cover before you ride, not after a claim.
Does homeowners insurance cover an e-bike?
Homeowners insurance may not cover an e-bike, because the standard home form can count it as a motor vehicle.
A plain bicycle is simple. The Insurance Information Institute (Triple-I, an industry research group) says bicycles are covered under the belongings part of standard home and renters policies. Theft and fire are paid, minus your deductible (the amount you pay first on a claim).
A motor changes that. Nevada publishes the home policy forms that insurers file here. Most come from ISO, the Insurance Services Office, a group that writes standard policy wording.
In the standard ISO home form, a "motor vehicle" means "a self-propelled land or amphibious vehicle." An e-bike's motor can put it inside that line. That is how many insurers read it.
The same form then lists motor vehicles as property it does not cover. It writes back only two small exceptions. Both apply to vehicles that do not need registration. They cover only one used to service the home, or one built to help a person with a disability.
A bike you ride to the store or around Lake Las Vegas fits neither exception. So under that standard wording, the bike itself can be left out, even when it is stolen from your own garage.
Insurers can and do change this wording. Some add e-bikes back in with an endorsement (a written change to the policy), often up to a set dollar limit. Your own policy decides, which is why the question belongs in writing. The guide to personal property coverage explains how the belongings part of the policy works.
| What happened | Standard home form | What can fill the gap |
|---|---|---|
| Your plain bicycle is stolen from the garage | Usually paid as belongings, minus the deductible | Nothing extra needed for most bikes |
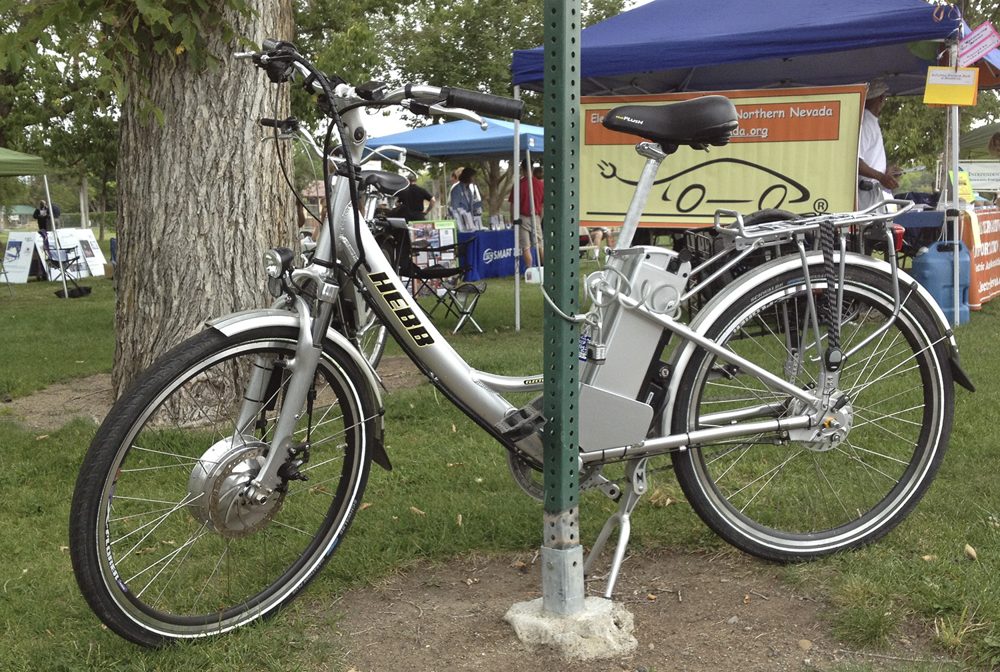
| Your e-bike is stolen from the garage | Can be left out as a motor vehicle | An insurer's e-bike endorsement or a separate e-bike policy |
| You hit a pedestrian on a Henderson street | Motor vehicle liability is left out off your property | E-bike liability cover; an umbrella (extra liability cover on top) may help |
| Your teen crashes into a parked car | Same motor vehicle rule as above | E-bike liability cover that lists household riders |
| A charging battery starts a garage fire | Fire damage to the house is a covered cause | The bike itself still needs its own cover |
| A car hits you while you ride | Your own injuries are not a home policy item | Health insurance; ask about your auto policy's uninsured motorist cover |
Do you need insurance for an e-bike in Nevada?
No. Nevada does not require insurance, registration or a plate for an e-bike that meets the state's definition.
The key line sits in the chapter that sets Nevada's car insurance rules. It defines "motor vehicle" and then leaves e-bikes out on purpose.
"Motor vehicle" means every self-propelled vehicle which is designed for use upon a highway ... The term does not include electric personal assistive mobility devices as defined in NRS 482.029 or an electric bicycle as defined in NRS 484B.017.
Nevada Revised Statutes 485.050. leg.state.nv.us
Nevada's registration chapter does the same thing. NRS 482.135 keeps electric bicycles out of the word "vehicle," so the DMV has nothing to register.
Notice the gap between the two rulebooks. State law says an e-bike is not a motor vehicle. Your home policy uses its own definition, and it can say the opposite. The policy's definition is the one that decides a claim.
Riding rules still apply. Under NRS 484B.763, a person on an e-bike has the rights and duties of a driver on the roadway. So a crash you cause can bring the same kind of injury claim a car crash can.
| Type | How the motor helps | Assisted top speed | State registration or insurance |
|---|---|---|---|
| Class 1 e-bike | Only while you pedal | 20 mph | Neither required |
| Class 2 e-bike | Can move the bike without pedaling, like a throttle | 20 mph | Neither required |
| Class 3 e-bike | Only while you pedal; needs a speedometer | 28 mph | Neither required |
| Moped | Motor up to 1,500 watts | 30 mph | Registration and plate required; liability insurance not required |
Every e-bike class has working pedals, a seat and a motor of no more than 750 watts. Since January 1, 2022, makers must put a label on each e-bike showing its class, top assisted speed and motor wattage. That label is worth a photo for your records.
Who pays if you hit someone on your e-bike?
Under the standard home form, your home policy usually does not pay for a crash you cause on a public street. Motor vehicle liability is left out.
Liability coverage is the part of a policy that pays when you are legally responsible for someone else's injury or property. It is usually the most valuable part of a home policy. The plain guide to liability coverage covers how it works.
The standard ISO form removes motor vehicle claims from that liability part in two steps.
- Step one leaves out any motor vehicle that is registered, or that the law requires to be registered. A true Nevada e-bike needs no registration, so it passes this step.
- Step two still leaves out every other motor vehicle, unless it fits a short list. The list includes a vehicle in storage and one used to service the home. It also includes one built to help a person with a disability, an off-road recreation vehicle on your own property, and a golf cart on a golf course.
A ride down Eastern Avenue fits none of those. The same rule also reaches medical payments to others, the small no-fault medical cover on a home policy. So a guest's bills are not paid there either.
Your car policy is unlikely to help. Triple-I says a standard personal auto policy leaves out liability for vehicles with fewer than four wheels. It says that about e-scooters, and an e-bike also has fewer than four wheels.
A golf cart runs into the same wall once it leaves your driveway. The Henderson golf cart insurance guide walks through that twin case.
Does an umbrella policy cover an e-bike accident?
An umbrella policy may cover an e-bike accident, but only as far as its own terms allow, so check before you count on it.
An umbrella is extra liability insurance that sits on top of your home and auto limits. Triple-I says a standard personal umbrella does not usually leave out vehicles with fewer than four wheels. So it may give some cover for e-scooter liability, and the same logic can reach an e-bike.
Two catches matter. First, an umbrella is built to pay above an underlying policy, and it names the minimum limits you must carry underneath. If nothing underneath covers the e-bike, the umbrella's own terms decide what it pays and what you pay first.
Second, umbrella wording varies by insurer. Ask the umbrella insurer to confirm in writing that your e-bike is a covered exposure.
The umbrella insurance guide explains how that extra layer is built and how much of it people usually carry.
The Valley West take
Send your home insurer one written question. "Does my policy cover my e-bike if it is stolen? Does it cover me if I injure someone while riding it on a public street?" Ask for the policy form number and any e-bike endorsement in the reply. Two yes answers mean you may need nothing more. Anything else is your gap.
When is an e-bike not an e-bike under Nevada law?
An e-bike stops being an e-bike in Nevada when it has no working pedals, a motor over 750 watts, or a top assisted speed above the class limits.
This is the edge case that surprises owners of fast "e-bikes" bought online. Once a bike falls outside NRS 484B.017, it is no longer an electric bicycle in state law.
A bike with a motor of up to 1,500 watts that tops out at 30 mph fits the Nevada DMV's moped description. A moped must be registered and carry a plate, and the person riding it needs a driver's license of any class. Liability insurance is not required for a moped.
That registration rule matters for insurance. The standard home form's first step leaves out any vehicle that the law requires to be registered. So a moped is outside the home policy's liability part from the start.
Anything faster or stronger can fall into motorcycle rules. There, Nevada requires at least $25,000 per person and $50,000 per crash for injuries, plus $20,000 for property damage. The Las Vegas motorcycle insurance guide covers that side.
Changing a bike can change its category too. Under NRS 484B.784, anyone who modifies an e-bike's speed or how its motor engages must replace the class label. A tuned bike with an old label is a problem for both the law and a claim.
What are Henderson's e-bike rules?
Henderson allows pedal-assist e-bikes on its roads, parks and trails, and bans throttle-only e-motorcycles anywhere in the city.
A vehicle without operable pedals that is powered solely by a throttle is classified as an e-motorcycle. E-motorcycles are illegal to operate anywhere in the City of Henderson, including public roadways, trails, parks, paths and sidewalks.
City of Henderson, Ride Smart. Stay Safe. Bike and Scooter Safety page. cityofhenderson.com
The city's page lists the rest of the current rules.
- Helmets. Everyone under 18 must wear a helmet on a bicycle, e-bike or e-scooter.
- Equipment. A front white light, a rear red reflector, a bell or horn, and working brakes.
- What a legal e-bike is. Working pedals, pedal assist, and a limit of 28 mph.
- Prohibited riding. Stunts, reckless riding, and speeds over 15 mph unless a different limit is posted.
- Parents. Parents and legal guardians may be liable for a child's unsafe or reckless e-bike use.
The park and trail rule dates to an ordinance the city announced on May 6, 2025, in Henderson Municipal Code Section 2.27. Pedal-assist e-bikes stayed welcome on trails and paths. Throttle-driven electric motorcycles did not.
That parent rule is the insurance point. If a teen in your home causes a crash, the claim can land on you. Under the standard home form, that claim is the same street-riding claim the policy leaves out.
Does home insurance cover an e-bike battery fire?
Home insurance treats fire damage to your house and belongings as a covered cause of loss under the standard form, even when a charging e-bike battery started it.
The motor vehicle wording removes the bike from the belongings list. It does not remove fire as a covered cause for the rest of your home. So a garage fire is a normal fire claim, subject to your deductible and limits.
The bike itself is a separate question, and the same gap applies to it. Battery fires are not rare. The CPSC (Consumer Product Safety Commission) counted 19 e-bike deaths tied to lithium-ion battery fires from 2017 through 2024.
Use the charger that came with the bike and follow the maker's charging directions. Tell your insurer about any home fire right away, in writing.
What could an uncovered e-bike claim cost you?
An e-bike claim your insurance does not cover can cost you the full price of the bike. It can also cost you the full amount of an injury claim against you.
E-bike injuries are no longer rare. The CPSC's April 2026 report shows how fast the numbers grew.
Of the 155,200 ED visits, the 2024 ED-treated injury estimate of 59,200 accounts for 38 percent while reflecting an increase of 52,900 ED visits from the annualized average estimate between 2017 through 2021 of 6,300.
U.S. Consumer Product Safety Commission, Micromobility Products-Related Deaths, Injuries, and Hazard Patterns 2017-2024, April 2026. cpsc.gov
The same report counts 310 e-bike deaths from 2017 through 2024. Collisions with cars or trucks caused 170 of them. Thirteen pedestrians died after being struck by an e-bike, which is exactly the kind of claim a person on an e-bike can face.
Here is the arithmetic on two made-up Henderson cases. It is illustrative only, not a quote and not a determination of coverage.
| How the policy treats the e-bike | Policy pays | You pay |
|---|---|---|
| Standard wording, no e-bike cover | $0 | $3,200 |
| Home policy covers it as belongings | $2,200 | $1,000 |
| Home policy covers e-bikes up to $1,500 | $500 | $2,700 |
| Separate e-bike policy, $100 deductible | $3,100 | $100 |
The math is simple. $3,200 minus the $1,000 deductible is $2,200. With a $1,500 cap, $1,500 minus $1,000 leaves $500, so you carry $2,700. With the separate policy, $3,200 minus $100 is $3,100.
Case B is the bigger risk. Say you hit a pedestrian on a Henderson street and the claim is $120,000. Under the standard home wording, the home policy pays $0.
With a made-up $100,000 e-bike liability limit, that policy pays $100,000 and $20,000 is left over. A $1,000,000 umbrella that accepts the e-bike could pay that $20,000. With no e-bike cover at all, the whole $120,000 is yours.
Check your e-bike against your own policy
Valley West Insurance will read your home policy with you. Page reviewed September 27, 2026. Bring your declarations page (the one page summary of your policy). You will get a plain-English read on how it treats an e-bike, for theft and for riding.
Educational information only, not a quote or a binding offer of insurance, and coverage is subject to carrier underwriting, eligibility and availability.
Review my e-bike coverageHow do you insure an e-bike in Henderson?
Insuring an e-bike in Henderson starts with confirming what your home policy does. Then add an e-bike endorsement or a separate e-bike policy for whatever is missing.
| Option | Theft and damage | Liability when you ride | Best fit |
|---|---|---|---|
| Home policy as written | Only if its form includes e-bikes | Rarely on public streets | Confirming, not assuming |
| E-bike endorsement on the home policy | Often, up to a set limit | Depends on the wording | A lower-priced bike, if liability is included |
| Separate e-bike policy | Usually, with its own deductible | Often offered as a choice | Riders who commute or ride often |
| Personal umbrella | No | May respond, per its terms | A high layer above other liability cover |
Scheduling is another path for an expensive bike. A schedule lists one item at an agreed value, and the guide to scheduled personal property explains how that works. Ask whether your insurer will schedule an e-bike, because some will not.
Before you shop, gather four things. You need the bike's class label, the receipt, the serial number and a few clear photos. Those same records help most after a theft.
If you are also buying a Henderson home, the home policy is set up before closing day. Our sister company, Valley West Mortgage, works on the other side of that closing. Ask about the e-bike when the new home policy is written, not a year later.
The wider Henderson picture, from the roof to the pool, is in the Henderson home insurance hub.
The bottom line
Nevada treats an e-bike like a bicycle, so no one makes you insure it. Your home policy may treat the same bike like a motor vehicle, and leave it out.
Find out which one you have now. A single written question to your insurer tells you whether theft and street riding are covered. If they are not, an e-bike endorsement or a separate policy closes the gap for a known cost.
A dog, a pool and a teen on an e-bike all raise the same question about your liability limit. The Henderson dog bite liability guide works through that limit with real claim numbers. The insurance glossary explains any term on this page in one line.
Close your e-bike gap before you ride
Valley West Insurance will walk through your home and liability cover with you. Page reviewed September 27, 2026. Bring your declarations page and your e-bike's class label.
Valley West Insurance is an independent insurance agency, not an insurer, and places coverage with licensed carriers. Educational information only, not a quote or a binding offer of insurance.
Start my Henderson e-bike reviewArticle history
- September 27, 2026. Published. Built on NRS 482.075, 482.135, 484B.017, 484B.763, 484B.784 and 485.050, and the ISO HO 00 03 05 11 home form as filed in Nevada. Also the Nevada DMV moped and insurance pages, the CPSC's April 2026 micromobility report, Triple-I guidance, and the City of Henderson's e-bike rules. All read on this date.
- September 27, 2026. Used the city's current rules page, not older news stories, for Henderson's helmet, equipment and speed rules. Quoted the state and city definitions word for word.
Frequently asked questions
Henderson e-bike owners ask these six questions most.
Does homeowners insurance cover e-bikes in Nevada?
Often not under the standard wording. The standard ISO home form calls a self-propelled land vehicle a motor vehicle and leaves most of those out, for theft and for riding.
Some insurers add e-bikes back with an endorsement. Your own policy decides, so ask your insurer in writing.
Do you need insurance for an e-bike in Nevada?
No. NRS 485.050 leaves electric bicycles out of the motor vehicles that need insurance, and NRS 482.135 leaves them out of registration.
That applies only to a bike that meets NRS 484B.017, with working pedals and a motor of no more than 750 watts.
Does car insurance cover an e-bike accident?
Usually not for liability. Triple-I says a standard personal auto policy leaves out liability for vehicles with fewer than four wheels.
If a car hits you, ask whether your own auto policy's uninsured motorist cover follows you on a bike.
Does an umbrella policy cover e-bike accidents?
It may. Triple-I says a standard personal umbrella does not usually leave out vehicles with fewer than four wheels.
Umbrella terms vary by insurer, and each one sets the limits you must carry underneath. Get written confirmation that your e-bike is covered.
Does home insurance cover a fire caused by an e-bike battery?
Fire damage to the house and your belongings is a covered cause of loss under the standard home form, subject to your deductible and limits.
The e-bike itself can still be left out as a motor vehicle unless your policy adds it back.
Are throttle e-bikes legal in Henderson?
A bike with no working pedals that runs only on a throttle is an e-motorcycle in Henderson. The city says those are illegal anywhere in Henderson.
The city's page says a legal e-bike has working pedals, uses pedal assist and is limited to 28 mph.
Sources
- Nevada Revised Statutes 484B.017, 484B.763 and 484B.784. Read September 27, 2026. leg.state.nv.us
- Nevada Revised Statutes 482.075 and 482.135. Read September 27, 2026. leg.state.nv.us
- Nevada Revised Statutes 485.050. Read September 27, 2026. leg.state.nv.us
- ISO Homeowners 3 Special Form HO 00 03 05 11 as filed in Nevada, Definitions, Section I Property Not Covered and the Section II motor vehicle liability wording. Read September 27, 2026. doi.nv.gov
- Nevada DMV, Mopeds. Read September 27, 2026. dmv.nv.gov
- Nevada DMV, Nevada Liability Insurance Requirements. Read September 27, 2026. dmv.nv.gov
- U.S. Consumer Product Safety Commission, Micromobility Products-Related Deaths, Injuries, and Hazard Patterns 2017-2024, April 2026. Read September 27, 2026. cpsc.gov
- Insurance Information Institute, Spotlight on: e-scooters and insurance. Read September 27, 2026. iii.org
- Insurance Information Institute, Bicycle safety and insurance. Read September 27, 2026. iii.org
- City of Henderson, Ride Smart. Stay Safe. Bike and Scooter Safety. Read September 27, 2026. cityofhenderson.com
- City of Henderson, City of Henderson Ordinance Defines E-Bike Regulations in Parks and Trails, May 6, 2025. Read September 27, 2026. cityofhenderson.com
Related Henderson and Nevada insurance guides
Three more pages cover the rest of your Henderson liability picture.